The process of buying a home is an expensive affair and for many homebuyers, a home loan facilitates their dream of owning a house. One important aspect that the banks take into consideration whilst sanctioning a home loan to any buyer is their CIBIL score. Having a good CIBIL score can prove beneficial for the buyers in terms of getting their loan approvals faster and better interest rates.
Since Aashray Realtors has multiple properties for sale for the homebuyers to choose from, it is essential that the buyers have a fair amount of knowledge regarding what is the best CIBIL score for home loan approval. This blog aims at discussing the concept of a CIBIL score, the best score that a buyer should target while planning to buy a home, and inculcating necessary habits to maintain a good credit score.
What is a CIBIL Score?
A CIBIL score is a three-digit numeric summary of the borrower’s credit report. In India, credit scores are maintained by credit information companies, wherein the information is used by the lenders to evaluate an applicant’s creditworthiness.
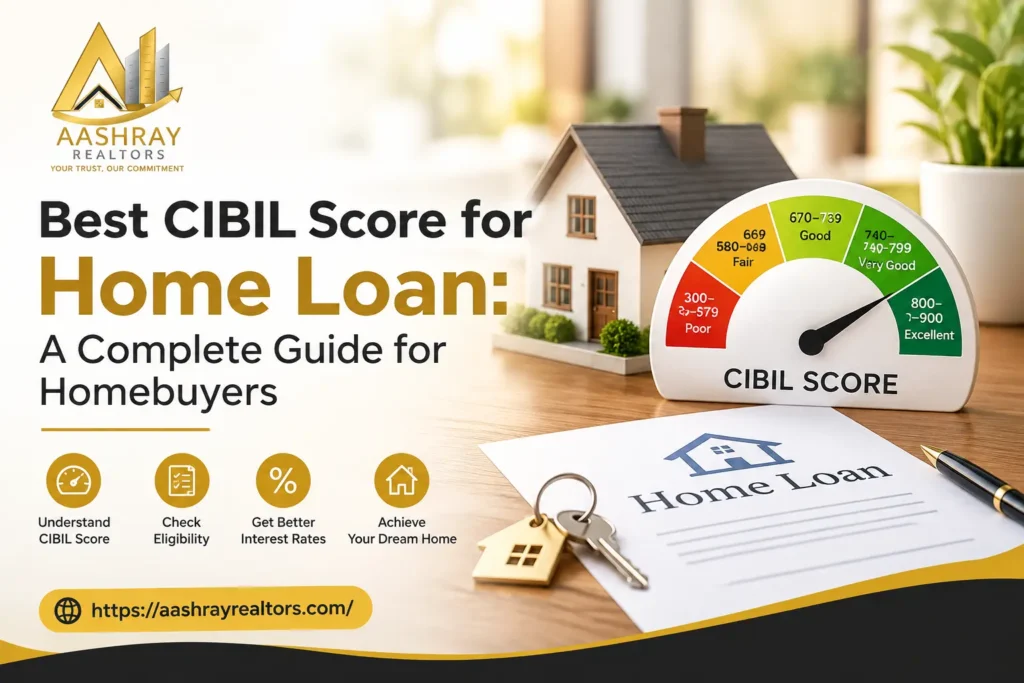
The CIBIL score generally ranges between 300 and 900. A higher score signifies a better credit history and therefore, a better chance of your loan approval. On the other hand, a low score would depict an unstable financial status and hence, a poor credit history.
Some of the major factors which play a major role in deciding one’s credit score are:
• Repayment history
• Credit utilisation
• Length of Credit History
• Credit Mix
• Number of Inquiries
• Outstanding Loans and Credit Card Balances
Before applying for a home loan, it is essential for the buyers to get a clear picture of their credit report, and accordingly, plan their finances.
What is the Best CIBIL Score for a Home Loan?
Since a home loan is a long-term financial liability, the lenders require a clear insight into the borrower’s credit standing. They assess the entire CIBIL score of the applicant to determine their eligibility for a home loan.
A score of 750 and above is considered as a good CIBIL score for the home loan applicants. This means that your credit profile is stronger as compared to the other borrowers. However, it must be noted that there is no specific score that determines the loan approval or rejection. This decision is taken on the basis of several criteria as determined by the banks such as income, occupation, liabilities, loan amount, property value, and repayment capacity. A simple depiction of CIBIL score range has been provided below:
CIBIL Score Range Credit Profile
| CIBIL Score Range | Credit Profile |
| 750 – 900 | Strong |
| 700 – 749 | Generally a Good Credit Profile |
| 650 – 699 | May Face Challenges in Approval |
| 600 – 649 | A Poor Credit Profile |
| Below 600 | Extremely difficult to get Approved |
The above-mentioned credit score range will give a clear idea to the applicants regarding their position as far as credit standing is concerned.
Why Does a CIBIL Score Matter for a Home Loan?
There are several factors that matter when a person applies for a home loan. A good CIBIL score will reflect a sound financial standing of the borrower, and depending upon the policies of the bank, here are certain advantages that one holds while having a good credit score:
1. Higher Chances of Home Loan Approval
A good credit score ensures that the borrower has a consistent repayment record and is responsible enough to repay any liabilities. Although one cannot solely rely upon their credit score for a home loan approval, it does increase the possibility of loan approval.
1. Fluctuating Interest Rates
Depending upon the CIBIL score of the borrower, one might get lower interest rates on their home loan as compared to others. Since a loan is a long-term financial liability, one must try to get the maximum benefits as far as the interest rates are concerned.
1. Higher Approval Amount
Eligibility for a home loan depends upon a series of documents, personal, as well as financial profiles of the applicants. Although your income, monthly savings, and repayment record play an important role in determining the loan amount, a good CIBIL score increases the possibility of getting approved with a higher loan amount.
1. Streamlined Process
When a borrower has a good credit history, it minimizes the chances of discrepancies in their financial records. Not only this, with a good credit score, a borrower is able to make better financial decisions and therefore, can be well-prepared for the home loan process.
Factors Affecting Your CIBIL Score
Since it is extremely essential to maintain a good credit score, one must be acquainted with the major factors that lead to a decline in one’s credit score:
1. Payment History:
Your repayment history plays a vital role in building a good credit profile. Any sort of late payment, default, or non-payment of your credit card bills or loan instalments on time reduces your credit score. Subsequently, always pay your dues on time to keep your credit score intact. You can also utilise the services of automatic payments to ensure that your payments are not delayed.
2. Credit Utilisation:
Credit utilisation refers to the percentage of your available credit that you utilise on a regular basis. If your credit card limit is, say, Rs.1,00,000/- and your outstanding amount is Rs.80,000/-, then it depicts that a huge chunk of your credit is utilised. A high credit utilisation depicts a poor credit score.
3. Credit History:
A long and a stable credit history reflects a sound financial status, and therefore, increases one’s credit score. Closing your credit card accounts sooner than necessary diminishes your credit history length and therefore, reduces your credit score.
4. Multiple Credit Applications:
Applying for multiple credit cards and loans reduces your credit score owing to the numerous credit inquiries. If you are planning to apply for a credit card or a loan, make a list of your requirements and accordingly, shortlist the most suitable lender for you.
5. Credit Mix:
A healthy mix of secured and unsecured loans maintains a good credit score. However, one must not indulge in taking unnecessary loans in order to maintain a good credit mix.
How to Improve Your CIBIL Score Prior to Applying for a Home Loan?
If you are targeting a specific score range or you are planning to apply for a home loan in the near future, you can follow the aforementioned points in order to improve your credit score:
1. Pay your dues on time
One of the easiest ways to maintain a good credit score is to pay your instalments and credit card dues on time. Always keep track of your due dates, and in case, you miss any payment, ensure that you make the payment as soon as possible. Subsequently, you can also utilise the automatic payment mode to ensure that your payments are not delayed.
1. Reduce Credit Card Balances
One of the major ways to improve your credit score is to reduce your credit card balances. Since a high credit utilisation ratio reduces your credit score, try to keep your outstanding amount as low as possible.
1. Avoid taking unnecessary loans
Before applying for a home loan, it is better to avoid taking any sort of loan. Since a loan increases your financial liability, it reduces your repayment capacity.
1. Check your credit report
Your credit report provides you with information regarding all your outstanding dues, repayment record, etc. In case you come across any error in your credit report, you should immediately report to the concerned party to get it rectified.
1. Maintain discipline
Improving your credit score requires discipline on your part. Always ensure that you exercise moderation and utilise your credit responsibly.
Can I Get a Home Loan With a Low CIBIL Score?
Whilst a low CIBIL score complicates the home loan application procedure, it does not entirely rule out the possibility of a home loan approval. In such cases, since the borrower possesses a poor credit history, his application is evaluated with a more cautious approach.
The lender takes into consideration your income, repayment history, monthly liabilities, and other factors whilst determining your home loan eligibility. Moreover, the following
factors are also taken into consideration by the lenders:
• Monthly Income
• Employment or Business Status
• Existing Loans and EMIs
• Down payment
• Loan to Value Ratio
• Property
• Repayment History
• Co-applicant’s Profile
Consequently, if you are a homebuyer with a low CIBIL score, you might have to improve upon your financial standing or strengthen your application package to increase the possibility of your home loan approval.
Does a Co-Applicant Affect Home Loan Eligibility?
Applying along with a co-applicant strengthens your home loan application, especially if the co-applicant has a stable income source and a good credit score. However, it is essential to note that the decision of the lenders is based on their policies and other criteria. A co-applicant should also be aware of their liabilities alongside yours.
How Much Down Payment Should I Plan?
A CIBIL score is just one of the most crucial criteria that determine your home loan eligibility. Apart from that, the down payment also plays a major role. The higher the down payment, the lesser the loan amount. Consequentially, a lesser loan amount means a lower EMI as well. However, before deciding on how much you should contribute towards the down payment, it is essential to keep in mind that you must not empty your savings account. Additionally, you should also account for any additional expenditure on the property.
Conclusion
The best CIBIL score for home loan is anything above 750. However, there is no specific score that determines your loan approval or rejection. There are several aspects that one must consider prior to buying a house. Having a sound financial profile improves the possibility of one’s loan being approved. The CIBIL score depicts an individual’s financial standing, and so, it is essential to build a good credit history.
For a home loan applicant, it is vital to keep in mind that getting pre-approved for a loan is of utmost importance prior to purchasing any house. A good credit score enables you to understand your finances better, and utilising proper financial planning can help you determine your budgets for the house purchase as well as your other expenditures. For the homebuyers who are planning to purchase a house in Noida, Greater Noida, Delhi NCR, Mathura, Vrindavan, and other locations, Aashray Realtors can assist them in acquiring the desired property with ease.
Aashray Realtors helps the buyers in exploring the diverse range of properties for sale. We aim at providing you with the much-needed assistance that helps you through a hassle-free house hunting experience.